Market overview of the Insulation Products Market
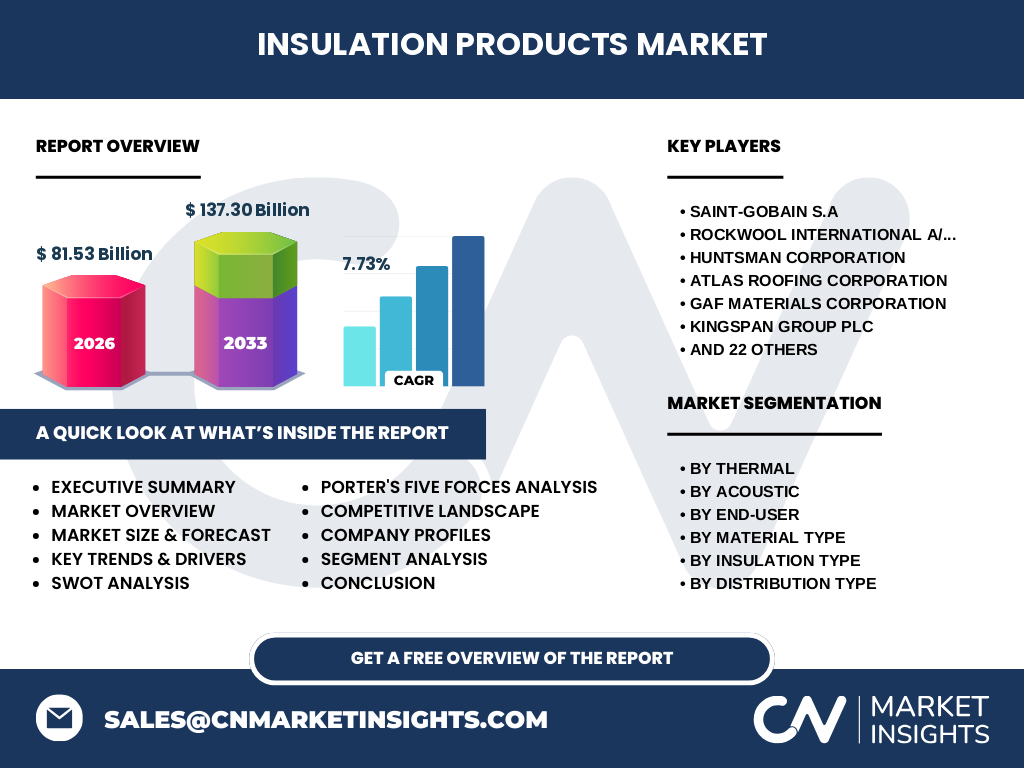
Our analysis indicates that the Insulation Products Market is valued at $81.53 Billion in 2026, establishing a critical structural baseline for global energy efficiency. The industry encompasses thermal, acoustic, and specialized fireproof or moisture control barriers. Key raw inputs like silica sand, basalt, and petrochemicals flow through major maritime hubs to supply stringent regulatory frameworks enforced by bodies like ASHRAE and the European Union's Energy Performance of Buildings Directive.
What are the key market drivers, restraints, challenges, and opportunities shaping the Insulation Products Market?
Strict decarbonization mandates act as primary drivers, forcing commercial real estate to adopt high-performance polyurethane foam and stone wool. Conversely, volatile petrochemical feedstock costs and supply chain bottlenecks at ports like Rotterdam present persistent restraints. Opportunities thrive in retrofitting aging European housing stock with eco-friendly insulation, though compliance with complex regional fire safety codes remains a steep industry challenge.
Emerging trends and growth patterns in the Insulation Products Market
The market is witnessing a rapid shift toward sustainable solutions, notably bio-based and aerogel-based thermal insulation designed for ultra-low thermal conductivity. According to our research, demand for eco-friendly insulation is surging across metropolitan zones subject to strict municipal carbon caps. Innovators are heavily investing in circular economy manufacturing to reduce embodied carbon, directly altering procurement strategies for tier-one contractors.
How did the COVID-19 pandemic impact the Insulation Products Market and what is the recovery trajectory?
The pandemic caused severe supply chain fractures and labor shortages across major manufacturing clusters, temporarily stalling construction pipelines. However, post-pandemic recovery heavily favored green stimulus packages. Government-backed retrofitting initiatives in North America and Europe accelerated market resiliency, positioning the sector for robust expansion through 2033 as remote-work trends redirected capital toward residential energy upgrades.
Competitive benchmarking and strategic dynamics in the sector
The landscape features high market concentration among multinational giants like Saint-Gobain S.A., Owens Corning, and Kingspan Group plc. These industry leaders leverage aggressive vertical integration and proprietary chemical formulations to secure high-margin supply contracts. Smaller regional players compete via localized distribution networks and specialized acoustic panels, creating a dynamic ecosystem of M&A activity and portfolio diversification.
Executive summary of key findings regarding the Insulation Products Market
Driven by aggressive global net-zero targets, the Insulation Products Market is projected to surge from $81.53 Billion in 2026 to $137.30 Billion by 2033, expanding at a remarkable CAGR of 7.73%. Thermal insulation dominates consumption, while stringent building energy codes continuously elevate performance benchmarks, favoring technologically advanced conglomerates over legacy manufacturers.
Market forecast trajectory from 2027 to 2033
Our proprietary modeling demonstrates sustained momentum, forecasting the market to climb from its 2026 valuation to $137.30 Billion by 2033 at a 7.73% CAGR. This trajectory is underpinned by massive infrastructural investments in developing Asian economies and mandatory energy audits for commercial real estate across North America, cementing long-term revenue visibility for raw material suppliers.
Segmentation analysis across material, type, and end-user categories
Segmentation reveals distinct demand pockets: By Material Type, options include mineral wool, fiberglass, stone wool, polyurethane foam, and flexible elastomeric foam. By Insulation Type, it splits into thermal, acoustic, and fireproof variants. By End-User, applications span building and construction, industrial piping, transportation, and consumer goods, with building and construction holding the dominant volume share.
Regional market analysis and geographic distribution performance
Geographic performance varies significantly due to localized climate requirements and regulatory strictness. Europe leads in eco-friendly insulation adoption driven by EU Green Deal mandates, while North America prioritizes high-R-value polyurethane and fiberglass solutions for extreme seasonal temperature fluctuations. Meanwhile, Asia-Pacific represents the fastest-growing regional market, fueled by rapid urbanization in China and India.
In-depth regional review of key growth territories
In North America, stringent ASHRAE 90.1 standards propel demand for advanced commercial roof insulation. Europe's market is heavily influenced by national subsidies for residential deep-retrofits. In Asia-Pacific, rapid industrialization necessitates heavy consumption of industrial-grade mineral wool and flexible elastomeric foam, supported by expanding manufacturing infrastructure in Southeast Asia and domestic trade hubs.
Company profiles and strategic positioning of leading enterprises
Industry titans like Rockwool International A.S. and Knauf Insulation GmbH focus heavily on sustainable stone wool manufacturing. Basf SE and Covestro AG anchor the chemical supply chain, innovating high-efficiency polyurethane precursors. Meanwhile, Armacell International Holding GmbH and L'ISOLANTE K-FLEX S.p.A. dominate the flexible elastomeric foam segment, targeting specialized HVAC and cryogenic industrial applications.
Porter's Five Forces analysis of the Insulation Products Market
Supplier power remains moderate due to consolidated petrochemical and mineral raw material markets. Buyer power is tempered by strict certification requirements that limit switching between certified thermal brands. Threat of substitutes is low in high-performance sectors, but rivalry is fierce among top-tier enterprises competing on thermal efficiency ratings and global distribution scale.
SWOT analysis highlighting internal capabilities and external pressures
Strengths include robust product portfolios and proprietary thermal technologies from firms like Saint-Gobain S.A. and Owens Corning. Weaknesses involve high carbon footprints in traditional foam production. Opportunities lie in emerging aerogel and eco-friendly segments. Threats stem from fluctuating raw material tariffs and stringent cross-border environmental compliance checks.
Value chain analysis from raw materials to end-users
The value chain initiates with upstream chemical refiners and mineral extractors sourcing silica, basalt, and polyols. Midstream manufacturing involves energy-intensive curing and foaming processes conducted by firms like Atlas Roofing Corporation and Johns Manville Corporation. Downstream distribution flows through online portals and localized offline stockists to reach general contractors and industrial end-users.
Investment insights and strategic high-potential areas
Investors should target greenfield manufacturing assets producing zero-emission aerogel and bio-based foams, as these align directly with corporate ESG commitments. Partnerships with regional logistics providers operating out of key ports will be vital to mitigate supply chain friction. Companies possessing proprietary fire-retardant technologies represent prime targets for venture and private equity deployment.
Conclusion and key strategic takeaways
The Insulation Products Market is transitioning from a commodity-driven sector to a high-technology, performance-critical industry. Surging toward $137.30 Billion by 2033, success will depend on agility in navigating stringent environmental regulations, raw material cost management, and continuous R&D investment in eco-friendly acoustic and thermal solutions.
Research methodology used to triangulate market estimates
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with C-suite executives at firms like Kingspan Group plc and BASF SE, and secondary macroeconomic indicators from global construction indices. Quantitative econometric models validate revenue projections against historical shipment volumes and regional building permit data.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market dynamics for insulation products from 2026 to 2033, segmented comprehensively by material, type, insulation category, distribution channel, and end-user. Limitations include unforeseen geopolitical trade shocks and sudden regulatory shifts in developing economies that may temporarily distort localized pricing indices.
Recent developments, strategic partnerships, and product launches
Recent market activities highlight aggressive capacity expansions; for instance, Owens Corning and Saint-Gobain S.A. have announced multi-million dollar investments in recycled-content manufacturing lines. Strategic acquisitions of regional acoustic insulation specialists by conglomerates like Knauf Insulation GmbH underscore an industry-wide push to consolidate market share in green building certification sectors.